Paper Profits Don't Settle Payroll: The Paradox of Booming Sales and Empty Accounts
At quarterly board meetings across growing enterprises, leadership celebrates: "Top-line revenues expanded by 40%, and net accounting margins surpassed $5 million!" Yet just two weeks later, the Chief Financial Officer enters crisis mode: treasury reserves are drained, bank overdrafts hit their ceiling, and operating liquidity is insufficient to meet upcoming payroll or honor critical supplier invoices.
This fatal commercial paradox is known across executive finance as "The Liquidity Cash Trap". The sober reality that founders frequently discover too late is that companies rarely go bankrupt from lack of paper profits; they collapse when they exhaust operating cash. In this manual, we unpack the executive levers required to insulate your balance sheet and accelerate your cash conversion velocity.
Strategic Index:
The Accrual Illusion: Why P&L Statements Obscure Cash Reality
The root cause of corporate insolvency lies within the fundamental divergence between two accounting doctrines: Accrual Accounting and Operational Cash Flow:
- Accounting Profit: Recognized the moment an invoice is generated and legal ownership transfers, regardless of whether client settlement occurs 180 days later.
- Operational Cash: The liquid balance physically residing in corporate clearing accounts today, unencumbered and immediately deployable to settle legal obligations.
The Iron Law of Corporate Solvency
"Revenue is vanity, profit is sanity, but cash is king—and cash flow is commercial reality."
An organization can survive for fiscal quarters without accounting profits (as evidenced by high-growth software and infrastructure ventures), but it will undergo forced liquidation in less than a fortnight if operating cash to satisfy debts is completely depleted.
The Frozen Capital Triangle: Where Does Your Liquidity Vanish?
If commercial revenue is accelerating yet liquidity remains strained, corporate capital has not vanished into thin air; it is mechanically imprisoned inside the Working Capital Cycle across three distinct silos:
1. Capital Trapped on Shelves
Raw materials or finished stock procured and paid for, sitting dormant in warehouse bays for months. Dormant inventory represents dead capital that bleeds carry costs, risks obsolescence, and demands ongoing insurance.
2. Unregulated Client Lending
Sales closed on open credit terms where collections drag out to 60 or 90 days. Extending undisciplined credit transforms your company into a commercial bank providing zero-interest working capital loans to your buyers.
3. Accelerated Vendor Outflows
Supplier invoices settled on premature 15-day schedules while customer collections lag at 75 days. This creates a severe 60-day funding void that must be bridged via costly credit lines or emergency cash injections.
Decoding the Strategic Formula: The Cash Conversion Cycle (CCC)
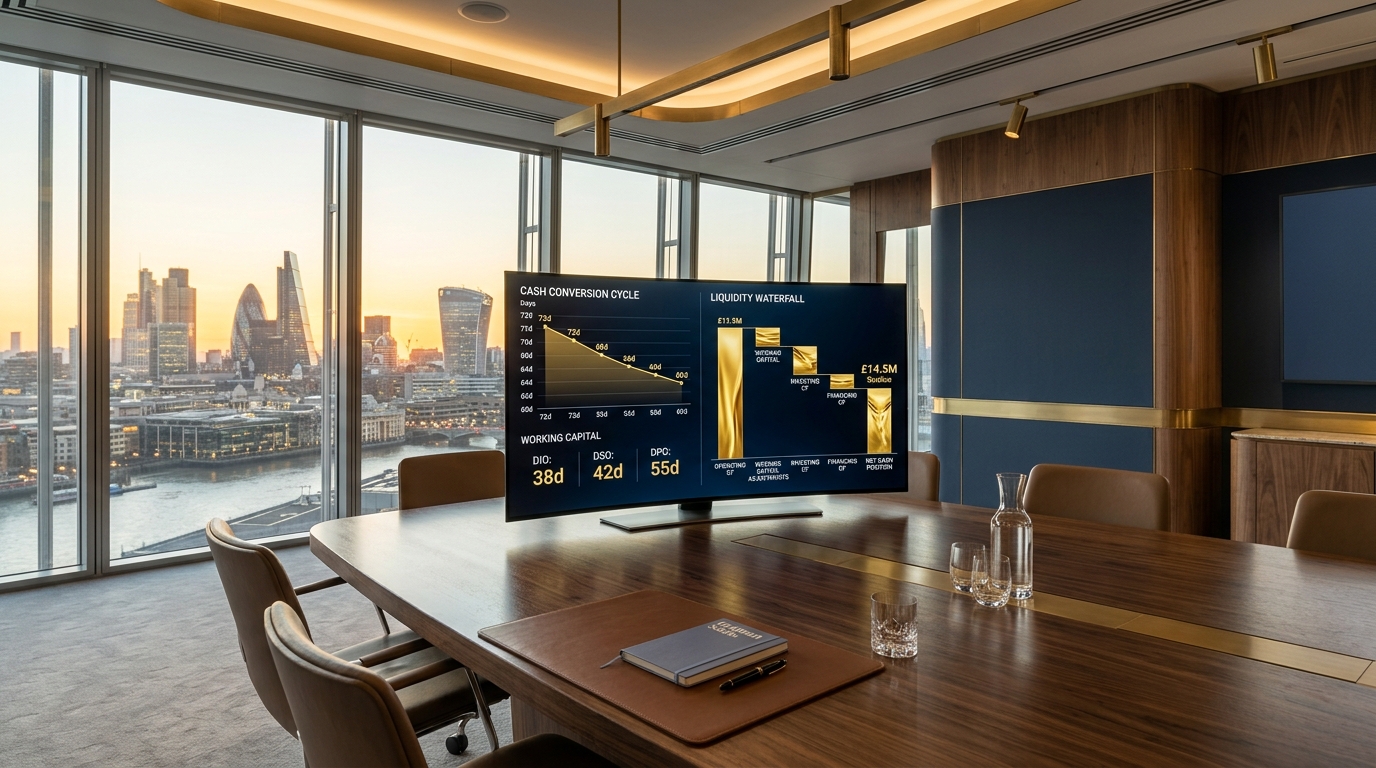
The Cash Conversion Cycle (CCC) is the most revealing operational diagnostic an executive can monitor. It answers a fundamental question: "How many days elapse from the moment a dollar leaves your treasury to purchase inputs until that same dollar re-enters your account alongside its commercial profit?"
A lower CCC indicates a lean, self-funding enterprise with high capital velocity. A bloated CCC signals operational friction and escalating vulnerability to liquidity shocks.
| Financial Benchmark | Enterprise A (Undisciplined Working Capital) | Enterprise B (Automated Working Capital) | Strategic Commercial Impact |
|---|---|---|---|
| Gross Sales & Net Margins | $50M (10% Net Margin) | $50M (10% Net Margin) | Both organizations exhibit identical commercial performance on paper! |
| Days Inventory Outstanding (DIO) | 85 Days (Overstocked) | 30 Days (Just-in-time velocity) | Enterprise B minimizes carrying costs and avoids product obsolescence. |
| Days Sales Outstanding (DSO) | 75 Days (Loose credit terms) | 35 Days (Automated credit gating) | Enterprise B captures operating capital a full 40 days faster. |
| Days Payable Outstanding (DPO) | 25 Days (Premature disbursements) | 50 Days (Negotiated strategic credit) | Enterprise B funds intermediate operations using vendor terms. |
| Net Cash Conversion Cycle (CCC) | 135 Days Deficit! | 15 Days Only! | Enterprise A requires $18.5M in debt lines to survive; Enterprise B needs merely $2M! |
The Three Operational Levers: Orchestrating Corporate Liquidity
Releasing trapped cash does not require taking on debt. It requires training operational divisions to coordinate three interconnected levers:
Lever 1: Transforming Stagnant Stock into Velocity (DIO)
Procurement teams frequently succumb to bulk vendor volume discounts: "Order 10,000 units for a 7% rate reduction!" Rigorous corporate finance proves that holding costs and capital drag range between 15% and 25% annually, wiping out the volume discount. The executive rule: **Buy only what moves within predictable demand cycles**.
Lever 2: Aligning Commercial Incentives with Collections (DSO)
Compensating sales reps purely on contract signatures incentivizes reckless terms to shaky buyers. Organizational culture must shift to: **"A sale is not complete until payment clears the bank"**, tying compensation directly to cash collection milestones.
Lever 3: Strategic Vendor Terms Negotiation (DPO)
Reliable suppliers prize predictable partnerships. Extending trade terms from 30 to 45 or 60 days while honoring agreed schedules grants your company an extra month of zero-interest working capital financing.
The Blueprint of Tech Giants: Manufacturing a Negative Cash Cycle
How did titans like Amazon and Dell finance rapid global expansions without crippling corporate debt? By engineering business models characterized by a Negative Cash Conversion Cycle.
The Negative CCC Advantage (CCC = -30 Days)
Non-Dilutive GrowthUnder this architecture:
Outcome: CCC = (18 + 2) - 60 = -40 Days! The company utilizes suppliers' operating float to finance corporate initiatives for 40 full days before liquidating payables.
For a production case study demonstrating how modern point-of-sale platforms enforce instant cash settlement across retail chains, explore my work: Two-Box POS Retail ERP System.
The Digital Remedy: How Modern ERP Guardrails Protect Treasury
Even well-conceived financial policies fail when dependent on manual oversight. Modern Enterprise Resource Planning (ERP) architectures act as automated, dispassionate enforcement mechanisms:
1. Automated Credit Gating
Defines strict credit ceilings and payment horizons per account. If a buyer exceeds thresholds, the system blocks new orders and restricts picking tickets until previous aging balances clear, eliminating interpersonal sales friction.
2. Predictive Cash Radar
Evaluates maturity dates across payables and receivables, rendering forward-looking cash flow projections that signal potential liquidity deficits 60 days in advance, allowing executive leadership to respond calmly.
3. Demand-Driven Procurement
Analyzes consumption velocity and vendor lead times to calculate precise reorder points, curbing slow-moving stock accumulation while ensuring raw materials arrive just in time for production.
To explore the architectural foundations of enterprise financial and inventory engines, inspect our definitive guide: Deconstructing Enterprise ERP: The Definitive Architectural Manual.
The CEO Action Plan: Unlocking Trapped Cash in 90 Days
To recover trapped liquidity and establish a self-funding growth trajectory, execute this 5-step operational blueprint:
Conduct ABC Inventory Rationalization
Identify non-moving stock dormant for over 180 days. Liquidate via promotional channels to immediately convert idle physical assets into operating cash.
Incentivize Early Customer Settlement
Offer 2% discounts for settlement within 10 days rather than 60. This accelerates cash flow at an effective cost far below bank borrowing rates.
Align Sales Commissions with Cash Receipts
Disburse 50% of commissions upon contract execution, holding the balance until full invoice settlement clears into corporate accounts.
Renegotiate Strategic Vendor Accounts
Extend payment windows to 45-60 days with primary vendors, leveraging consistent ordering history to unlock zero-interest float.
Automate Receivables Workflows
Transition from paper invoicing to digital channels with automated payment links and reminders dispatched 3 days prior to maturity.
Looking to Engineer Solvency and Accelerate Capital Velocity?
Digital Transformation & Enterprise Architecture Advisory with Ahmed Al-Gendy
Sustainable enterprise growth requires robust alignment between operational execution and treasury liquidity. Combining postgraduate research in Business Administration (MBA - AAMBFS) and Artificial Intelligence (AASTMT) with over 13 years of software engineering leadership, I assist executive teams in modernizing operations, deploying automated ERP guardrails, and unlocking trapped working capital.